Cryptocurrency Prices by Coinlib
Are Crypto-Backed Loans Protected? Dangers Defined

Quick reply:
Crypto-backed loans aren’t risk-free, however the threat could be measured and managed. Earlier than you get one, two issues matter most: how a lot you borrow in opposition to your collateral (your loan-to-value ratio, or LTV) and the way the lender handles falling costs.
Get each proper, and a crypto-backed mortgage is usually a sensible strategy to entry money with out promoting. Get them fallacious, and a market drop can value you a part of your holdings.
This information covers what to know earlier than you get a crypto-backed mortgage: the way it works, the actual benefits and dangers, and the inquiries to ask any lender first.
How crypto-backed loans work
A crypto-backed mortgage allows you to borrow in opposition to digital belongings you already personal, equivalent to Bitcoin (BTC), Ether (ETH), or stablecoins. You pledge the crypto as collateral, and the lender supplies funds, often in US {dollars} through financial institution switch or in stablecoins like USDC.
As a result of the mortgage is backed by collateral, most lenders do not run a credit score examine. As a substitute, they cap how a lot you may borrow with a loan-to-value (LTV) ratio. LTV is your mortgage quantity divided by the worth of your collateral. When you borrow $5,000 in opposition to $10,000 of BTC, your LTV is 50%.
Crypto costs can transfer 10% or extra in a day. When your collateral loses worth, your LTV rises, even when you have not borrowed one other greenback. Each crypto lender has a threshold the place it steps in, often by promoting a few of your collateral to repay a part of the mortgage. Within the business, that is referred to as liquidation.
The professionals: why folks borrow in opposition to crypto
You retain your place. Borrowing allows you to entry funds with out promoting belongings you count on to carry long run. If the value rises whereas your mortgage is open, you continue to profit from that upside when you repay.
Promoting can set off taxes; borrowing typically does not. Within the US, promoting crypto is often a taxable occasion. Taking out a mortgage in opposition to it typically is not, as a result of you have not disposed of the asset. Tax guidelines rely in your state of affairs, so examine with a professional tax skilled earlier than counting on this.
No credit score examine, sooner entry. For the reason that collateral backs the mortgage, approval does not rely in your credit score rating, and funds can arrive a lot sooner than with a financial institution mortgage.
Versatile compensation. Many crypto credit score merchandise haven't got mounted month-to-month installments. You repay when it fits you, so long as your LTV stays inside limits.
The cons behind crypto-backed loans
Value drops can power a sale of your collateral. This can be a frequent manner a mortgage can develop into more durable to handle. In case your collateral falls far sufficient, the lender sells a part of it to carry your LTV again down. You lose these cash at a low worth, and if the market recovers, you aren't getting them again.
Quick markets could transfer sooner than you do. Crypto costs can change rapidly, together with outdoors market hours. Alerts will help you retain monitor, however they don’t assure you’ll have time to behave.
The issue you management most: your LTV
Most crypto lenders allow you to borrow as much as 50% of the worth of BTC or ETH.
The LTV you begin with determines how massive a worth drop your mortgage can soak up earlier than the collateral is bought. Here is a labored instance utilizing an automated compensation threshold of 83.33% LTV, the extent Nexo makes use of when collateral is totally crypto:
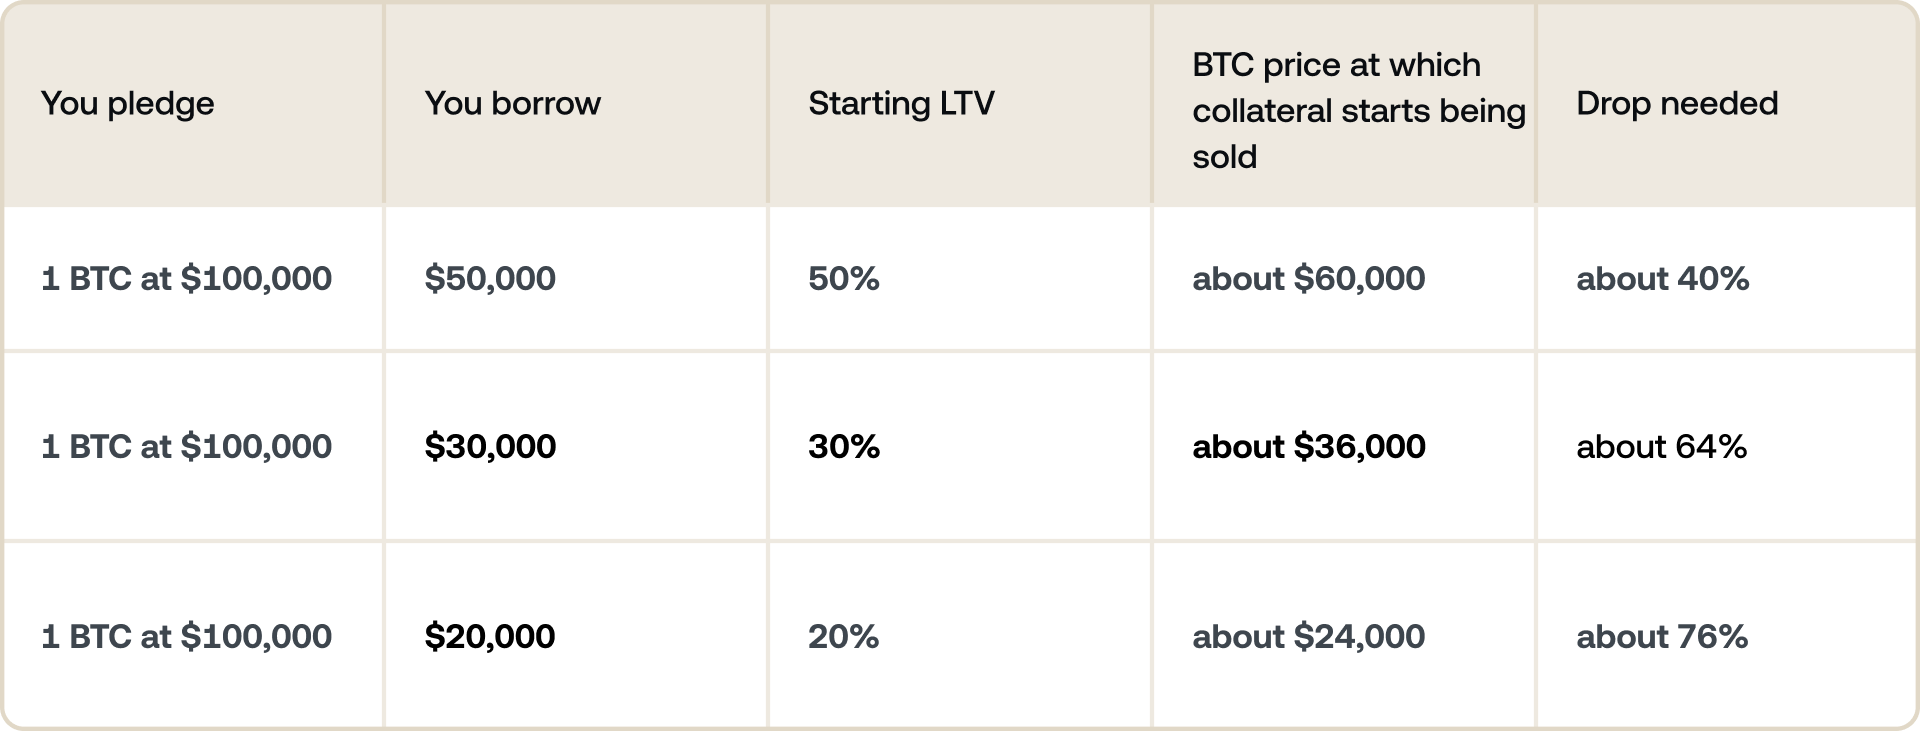
Illustrative figures solely. They ignore accrued curiosity, which raises your LTV over time. Not a forecast of future costs.
Borrowing lower than the utmost is the simplest threat management accessible to any borrower, with any lender. On Nexo, LTV at 20% or much less can get you decrease rates of interest, given you’re a part of the Wealth Club loyalty program.
Inquiries to ask earlier than you borrow
- At what LTV does the lender promote collateral, and the way a lot does it promote? Some lenders promote solely sufficient to revive a wholesome LTV. Others shut the entire place.
- Will I be warned earlier than that occurs? Ask how alerts work, and whether or not a sale can occur with out prior discover.
- What's going to I actually pay? Verify how the speed adjustments with LTV, whether or not curiosity compounds, and whether or not early compensation prices further.
- How do I repay, and is there a schedule? Verify whether or not you may repay in crypto, stablecoins, or US {dollars}, and whether or not minimal funds apply.
- What unbiased checks has the lender handed? Search for verifiable audits and certifications, not simply claims.
How Nexo's Credit score Line approaches these dangers
Nexo has provided crypto-backed credit score since 2018 and has a mortgage ebook of over $1.7 billion. Within the US, belongings used as collateral for Nexo’s Credit score Line are held in custody by Bakkt, a publicly listed US firm. Here is how the Credit score Line solutions the guidelines above.
Automated repayments are partial. In case your LTV reaches 83.33% (when your collateral is totally crypto), Nexo mechanically sells a part of your collateral to carry your LTV again to a more healthy stage first. When you maintain a mixture of crypto and stablecoins, the edge relies on that blend.
You may see the danger constructing. The Nexo app reveals your mortgage well being as Good, Reasonable, or Poor. Nexo additionally sends margin name emails as your LTV approaches the automated compensation threshold. These alerts are despatched on a best-efforts foundation. In quick markets, an automated compensation can occur earlier than you see one.
You may arrange an automated top-up. With Automated Collateral Switch turned on, Nexo strikes eligible belongings out of your Financial savings Pockets into your Credit score Pockets to decrease your LTV earlier than an automated compensation is triggered. A associated setting may also draw on belongings dedicated in a Mounted-term Yield.
Charges reward decrease LTV. Credit score Line charges rely in your Wealth Membership tier and your LTV. They begin at 0.9% per yr for Signature-tier purchasers whose Credit score Pockets LTV stays beneath 20%. Above 20% LTV, the usual charge for a similar tier is 7.9% per yr. Curiosity compounds, and also you solely pay it on the quantity you've got drawn for the times you employ it.
Reimbursement is versatile. There aren't any mounted compensation dates and no minimal installments, and you'll repay in crypto or stablecoins. Nevertheless, if you happen to repay inside 45 days of your final withdrawal, extra curiosity at 15.9% per yr applies to the repaid quantity for the remainder of that 45-day interval.
Collateral choices. You may borrow from $50 (in stablecoins) or $500 (by financial institution switch) as much as $2 million, in opposition to BTC, ETH, and 30+ different belongings. Most LTV is 50% for BTC and ETH and 90% for USDC and USDT. Nexo does not run a credit score examine.
Impartial audits. Nexo holds SOC 2 Sort 2 certification and ISO 27001, 27017, and 27018 certifications for data safety and knowledge dealing with.
See how borrowing work
Is a crypto-backed mortgage best for you?
A crypto-backed mortgage could go well with you if you happen to plan to carry your crypto long run, want funds for a selected objective, and might add collateral or repay rapidly if costs fall. It is possible a poor match if you happen to'd be pressured to promote in a downturn anyway, if you happen to'd borrow at or close to the utmost LTV, or if you happen to plan to make use of the funds to purchase extra crypto.
The most secure model of a crypto mortgage is a small one. Borrow nicely beneath the utmost, know precisely the place your lender's threshold sits, and select a lender that's clear about what it prices to borrow.
Incessantly requested questions
1. Are crypto-backed loans protected?
They might carry actual dangers. You may scale back it by borrowing nicely beneath the utmost LTV and selecting a lender with clear phrases, named asset holders, and unbiased audits.
2. Can I lose my crypto with a crypto-backed mortgage?
Sure. In case your collateral's worth falls far sufficient, the lender will promote some or all of it to repay the mortgage. You will not get these belongings again, even when costs get better.
3. What occurs if I am unable to repay a crypto mortgage?
With most crypto credit score merchandise, there is not any mounted due date, so lacking a cost is not the primary threat. The danger is your LTV rising. If it reaches the lender's threshold, collateral is bought to cowl the mortgage.
4. Do crypto-backed loans have an effect on my credit score rating?
Most crypto lenders, together with Nexo, do not run a credit score examine. Verify the lender's phrases to verify whether or not it experiences to credit score bureaus.
5. Is borrowing in opposition to crypto a taxable occasion within the US?
Taking out the mortgage typically is not, as a result of you have not bought something. If collateral is bought to repay the mortgage, that sale could also be taxable. Communicate to a professional tax skilled about your state of affairs.
6. What's a protected LTV for a crypto mortgage?
There isn't any LTV with out threat, however decrease is all the time extra resilient. At 20% LTV, BTC would wish to fall about 76% earlier than automated compensation begins at an 83.33% threshold. At 50%, a fall of about 40% is sufficient.
Borrowing in opposition to digital belongings entails threat. If collateral worth declines, you might be required so as to add collateral or repay promptly. The platform could execute partial or full automated repayments or collateral gross sales to handle loan-to-value thresholds, together with throughout fast-moving markets when notifications will not be well timed. Purchasers are answerable for monitoring their Mortgage-to-Worth ratio. Curiosity, charges, spreads, and different fees could apply and might change. Charges, product availability, options, and relevant phrases could differ based mostly on jurisdiction, eligibility, loyalty tier, and different components, and are topic to alter at any time. When phrases equivalent to “as much as” or “from” are used to indicate limits, attaining these most or minimal thresholds could also be conditional on extra actions or fulfilment of sure standards and necessities that will not be attainable by all purchasers. Any examples are for illustrative functions solely. This data doesn't represent tax recommendation. Please seek the advice of a professional tax skilled relating to your particular circumstances. For extra data, go to Bakkt Disclosures.
These supplies are accessible globally, and the supply of this data doesn't represent entry to the providers described, which providers will not be accessible in sure jurisdictions. These supplies are for normal data functions solely and never meant as monetary, authorized, tax, or funding recommendation, supply, solicitation, advice, or endorsement to make use of any of the Nexo Providers and usually are not personalised, or in any manner tailor-made to mirror explicit funding aims, monetary state of affairs or wants. Yield and rates of interest usually are not assured, are topic to alter, and should differ by eligibility, chosen time period, and wealth tier. References to Yield are product names and don't symbolize charges of return or efficiency. Nexo merchandise usually are not financial institution deposits and usually are not insured by the FDIC or SIPC. Digital belongings are topic to a excessive diploma of threat, together with however not restricted to risky market worth dynamics, regulatory adjustments, and technological developments. The previous efficiency of digital belongings will not be a dependable indicator of future outcomes. Digital belongings usually are not cash or authorized tender, usually are not backed by the federal government or by a central financial institution, and most should not have any underlying belongings, income stream, or different supply of worth. Impartial judgment based mostly on private circumstances must be exercised, and session with a professional skilled is really helpful earlier than making any determination.
Providers are supplied by Bakkt Crypto Options, LLC. Digital belongings could also be held or serviced by third-party custodians, exchanges, lenders, or different service suppliers. Your capability to entry or get better belongings relies on the supplier’s operational resilience and monetary situation. If a supplier turns into bancrupt or experiences an operational disruption, you might expertise delays in entry to belongings and will lose some or all your belongings. For extra data, go to Bakkt Disclosures.