Cryptocurrency Prices by Coinlib
Ethereum’s Summer time Actions

Whereas Half 1 mapped the place capital sat as of early 2026, this evaluation picks up the thread in June – when the summer season cycle started – and traces how that capital really moved by June 1 to September 1.Over the summer season, the Aggregated High-10,000 completed $13.9B richer – whereas holding nearly 0.9M much less ETH. On the similar time, Ethereum staking added 3.6M ETH. The identical season, two reverse instructions. That's the start line of this evaluation: the summer season rebound was not merely capital returning. It was capital altering type, use, and focus. This research makes use of the Aggregated Ethereum Handle Wealthy Checklist, constructed on the totalBalanceUsd metric, which aggregates the greenback valuation of ETH, ERC-20 tokens, and stablecoins. This strategy is essentially completely different from conventional rankings, which traditionally ranked holders solely by ethBalanceUsd. High-10,000 figures consult with month-to-month rating snapshots; the handle set might change between dates. Token contracts are excluded from the rating.Richer in {dollars}, poorer in ETHThe greenback worth of the Aggregated High-10,000 traced a V-shaped arc: $339.3B on June 1, a trough of $293.7B on July 1, then a restoration to $303.8B in August and $353.2B by September 1. A $13.9B internet acquire over the season.Nevertheless, their holdings of native ETH moved in the other way. Over the summer season, native ETH fell from roughly 54.1M to 53.1M ETH – a drop of almost 0.9M ETH, or 1.7%.August was significantly telling. In greenback phrases, the ETH element of the High-10,000 addresses surged by 32.8% – from $98.6B to $131.0B. At first look, this would possibly seem like heavy ETH accumulation by main holders. But bodily ETH holdings barely grew: roughly 99% of the greenback enhance within the ETH element was pushed solely by the worth revaluation of present ETH.In brief, the Wealthy Checklist did develop wealthier – however not as a result of whales have been aggressively shopping for ETH. It was primarily a valuation impact.Portfolio composition additionally shifted. Stablecoin balances fell by 8.3% over the summer season, whereas non-stable ERC-20 tokens ended the season roughly 1.6% above June ranges. Through the mid-summer drawdown, the share of stablecoins rose, however it dropped sharply throughout the August rebound. Whereas this doesn't show a direct conversion of stablecoins into ETH, it demonstrates that the restoration was not a easy reset of costs to baseline: the construction of noticed capital underwent a transparent shift.When venture progress is its personal tokenTo distinguish exterior capital from worth tied to a venture’s personal token, the evaluation makes use of the Printing Press Index (PPI).PPI = Personal-token worth / Whole ERC-20 worth throughout venture addresses.The upper the PPI, the extra of a venture’s token stability comes from its personal token – and the extra fastidiously one should interpret Aggregated stability progress as an influx of exterior capital.Summer time information illustrates how drastically this alters the interpretation of “venture progress.”Uniswap ended the summer season up roughly $773M (+39.5%). Nevertheless, about $648M of this enhance got here from its native UNI token – accounting for roughly 84% of the full acquire. The venture's PPI rose from 45.9% to 57.3%.For Chainlink, the impact was much more pronounced: complete attributed stability grew by roughly $507M, whereas the worth of LINK held on the venture's personal addresses elevated by $550M. In different phrases, native token progress accounted for 108.6% of your entire internet acquire: all different noticed property held by the venture collectively shrank over the interval. PPI climbed from 89.8% to 92.4%.World Liberty Monetary, a crypto venture co-founded by members of the Trump household, presents an excessive instance of one other sort. By September 1, roughly $3.8B of its ERC-20 worth consisted of its native WLFI token, pushing its PPI to 98.2%.That worth is economically actual – however it isn't equal to exterior capital. $1B in exterior property and $1B in a venture’s personal token characterize very completely different stability sheets.That's exactly why the subsequent stage of Wealthy Checklist evaluation goes past measuring totalBalanceUsd to evaluating the standard of progress: dissecting what really drove the rise in stability.ETH didn’t accumulate within the Wealthy Checklist – it turned productiveWhile the primary part demonstrates that the most important liquid addresses weren't accumulating native ETH, the staking layer reveals the precise reverse pattern.
Market-cap share of Whole market cap (ETH + tokens), not solely Ethereum provide.Caption
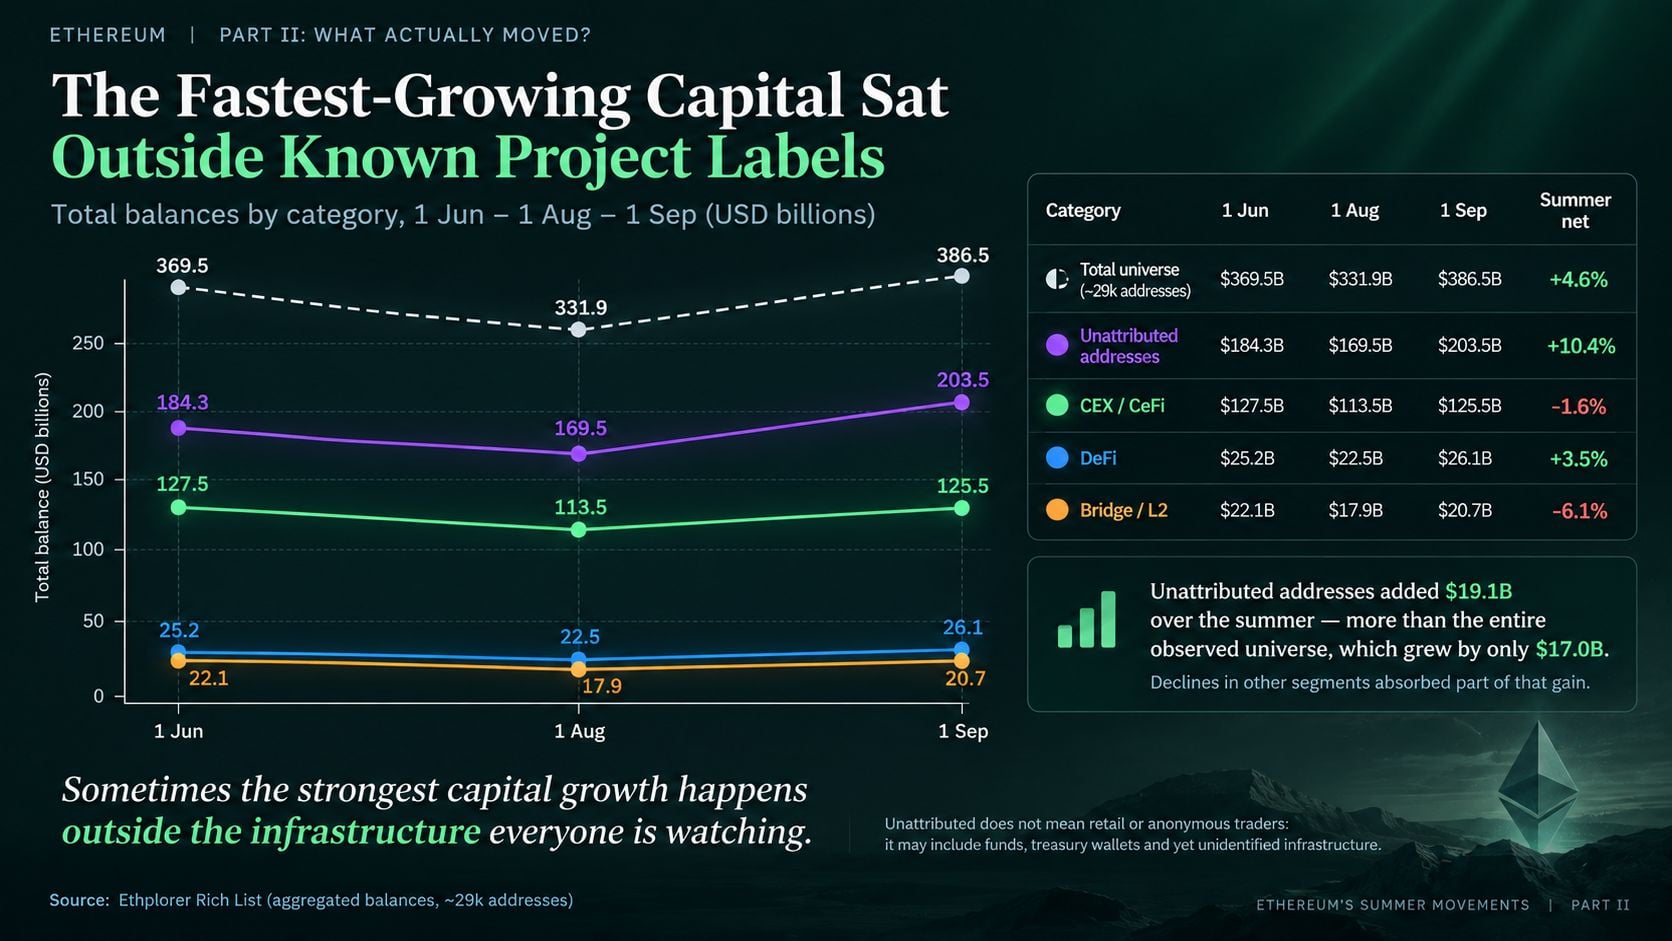
Over the summer season, energetic staking grew from 39.3M to 42.9M ETH – a rise of three.6M ETH, or 9.1%. Notably, staking continued to climb even during times of declining greenback valuations: by August 1, staked ETH had already risen to 41.5M, regardless of its complete USD worth dropping from $79.0B to $77.2B.To check this distinction, the evaluation expands the lens past the High-10,000. Throughout the broader noticed universe of roughly 29k giant addresses – quickly re-including token contracts to account for underlying ETH throughout the WETH contract – liquid and wrapped ETH balances fell by roughly 1.8M ETH over the summer season. In the meantime, staking absorbed an extra 3.6M ETH.The directional shift was constant month after month: liquid/wrapped balances declined whereas staking expanded. Whereas it's inconceivable to hint each particular person ETH unit on to a selected validator deposit, prohibiting definitive proof of a 1:1 switch, the sheer scale and synchronicity place staking as essentially the most pure rationalization for a significant portion of this motion.ETH was leaving liquid balances – however staking suggests a lot of it was being put to work, not merely leaving the ecosystem.Ether.fi: The Identical Staked ETH in a New FormThe case of Ether.fi (a liquid restaking protocol) exhibits how the staking stack itself was being reshaped. Its attributed stability jumped from $229M to $1.2B, however 97.6% of that enhance appeared in a single official Restaker contract (0x1b7a…6fff) – that means the change largely mirrored the place present staked capital turned seen, fairly than a fivefold enhance in TVL.That restructuring adopted a extreme spring stress take a look at: Ether.fi processed withdrawals equal to 19.6% of its beginning TVL after the Kelp rsETH incident. By August, primary staking had been separated from elective restaking, making the additional yield – and the additional danger – an specific consumer selection.This yielded a near-paradoxical constructive final result from the disaster: the sector turned extra cautious, structure grew extra clear, and the road between staking and restaking danger turned clearer to customers.Good-contract capital turned extra top-heavyAcross the broader Aggregated High-10,000, sensible contracts really misplaced floor over the summer season. Their rely dropped from 1,722 to 1,570, whereas complete capital shrank from $88.6B to $86.5B.On the very high of the Wealthy Checklist, nevertheless, the alternative occurred. Throughout the High-100, sensible contract capital grew from $41.6B to $44.7B.Viewing this by the lens of contract-capital focus makes the pattern even starker: in June, the High-100 held roughly 47.0% of all sensible contract capital throughout the High-10,000. By September, that share had risen above half, to 51.7%.The focus may mirror two completely different dynamics: capital actively consolidating into top-tier contracts, or lower-ranked contracts merely dropping worth quicker. The info can't distinguish between the 2, however both approach, the structural shift is evident. The Quickest-Rising Capital Sat Exterior Identified Venture Labels The ultimate main shift of the season considerations not asset composition, however attribution ranges.Throughout the complete project-attribution universe, complete noticed capital grew by roughly 4.6% over the summer season – from $369.5B to $386.5B. Nevertheless, unattributed addresses expanded at a a lot quicker tempo: from $184.3B to $203.5B, a ten.4% acquire.Because of this, their share of complete noticed capital rose from 49.9% to 52.6%, that means that by the tip of summer season, over half of all tracked capital resided in addresses with out specific venture labels.For comparability, the three essential classes of recognized infrastructure – CEX/CeFi (-1.6%), DeFi (+3.5%), and Bridge/L2 (-6.1%) – collectively contracted by 1.5%. Thus, unattributed addresses served as the first progress engine for your entire pattern.On the floor, stability progress outdoors established venture labels outpaced that of the recognized crypto infrastructure tracked right here.The strongest capital progress over the summer season occurred outdoors the infrastructure labels everybody was watching. Ultimate Perception: from balances to behaviorPart 1 redrew the map of Ethereum wealth.Half 2 reveals that even when the market rebounds to just about the identical greenback complete, capital throughout the ecosystem returns in a essentially completely different type.Ethereum’s largest balances recovered over the summer season, however the underlying capital didn't return to the place it began. ETH turned extra productive by staking. For a number of main initiatives, stability progress was pushed largely by their very own tokens. Good contract capital turned extra concentrated. And the fastest-growing capital sat outdoors conventional venture labels.The market recovered. Its capital construction didn't reset.
Disclaimer: This text is supplied for informational functions solely. It's not provided or meant for use as authorized, tax, funding, monetary, or different recommendation.